Does buildings insurance cover roof repairs? Yes, when the damage is caused by a sudden, insured event such as a storm, hail, fire or a falling tree. It will not pay for a roof that fails through wear and tear, ageing materials, poor workmanship or lack of maintenance.
Most rejected claims come down to one thing: the insurer says the problem built up over time. If you are claiming, show the damage was sudden and back it up with photos, dates and a report from a professional roof repair team.
Key takeaways
- Cover is limited to sudden, insured events such as storms, hail, fire or a falling tree.
- Wear and tear, poor maintenance, long-term leaks and faulty workmanship are almost always excluded.
- Act fast, photograph the damage and keep maintenance records to give a claim the best chance.
- A written report from a qualified roofer helps prove the damage was sudden rather than gradual.
What does buildings insurance cover?
Buildings insurance protects the structure of your property, not the contents inside it. That includes the roof and roof structure, walls and foundations, windows and doors, gutters, fascias and soffits, and garages and permanent outbuildings. Contents insurance is a separate policy.
When are roof repairs covered?
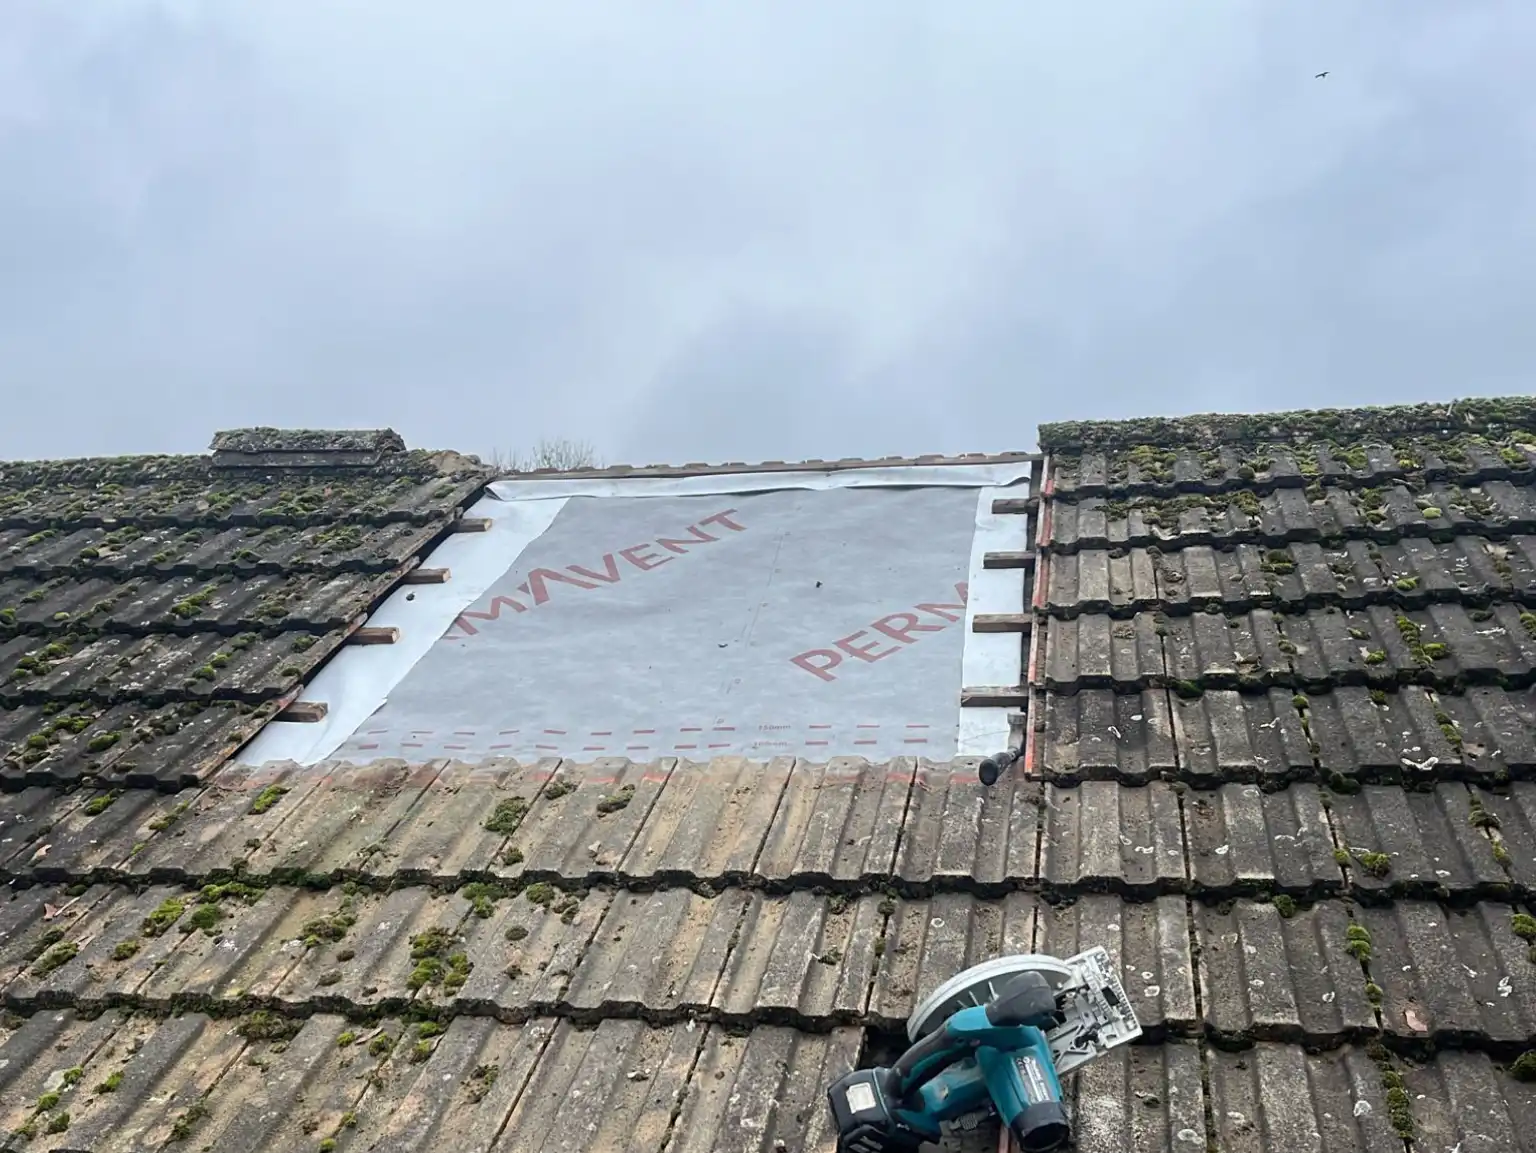
Buildings insurance covers roof repairs only when the damage is sudden and unexpected. Common examples:
- Storm damage: high winds, heavy rain or hail that lift, crack or blow off tiles. This is one of the most common accepted roof claims in the UK, though each policy defines what counts as a storm.
- Falling objects: a tree, branch or other debris landing on the roof.
- Fire, lightning or explosion: almost always covered.
- Impact damage: vehicles or other accidental impacts, depending on the policy.
In every case, insurers expect the roof to have been in reasonable condition beforehand.
When are roof repairs not covered?
This is where most claims fail.
- Wear and tear: cracked tiles, worn felt, thinning membranes and corroded fixings are classed as gradual deterioration.
- Poor maintenance: blocked gutters, moss build-up, loose flashing or slipped tiles that were left unfixed. Insurers will argue the damage was preventable.
- Long-term leaks: a leak that has developed over months is rejected in most cases, even if the damage is now severe.
- Faulty workmanship: problems caused by poor installation or cheap patch repairs.
- End of life: insurance will not pay to replace a roof just because it is old.
Why roof maintenance matters for a claim
Most policies require you to maintain the property. If you cannot show the roof has been looked after, insurers will use that against you. Basic maintenance means clearing gutters and outlets, replacing broken or missing tiles, securing loose ridge tiles, checking flashing and roof junctions, and dealing with moss and debris. Keep invoices and photos of any work, because they can make the difference between approval and rejection.
How to improve your chances of a successful claim
- Report it straight away. Delays raise red flags.
- Take photos and video from several angles before anything is cleared up or repaired.
- Prevent further damage. Temporary protection or an emergency repair shows you took reasonable steps, which insurers expect. Keep the receipt.
- Get a professional report. A written assessment from a roofer helps prove the damage was sudden and not ongoing.
- Keep maintenance records. Invoices, inspection reports and earlier photos all support your case.
Are flat roofs treated differently?
Flat roofs get more scrutiny. Ponding water, cracked membranes and sagging decks are often blamed on design or maintenance rather than a sudden event, so keeping a flat roof in good repair is the best way to protect a future claim. Storm damage to a flat roof can be covered, but only if it was in good condition and properly maintained beforehand.
Is it worth claiming for a small roof repair?
Often not. Many roof repairs cost less than, or close to, a typical policy excess, and a claim can push up your premium for years. As a guide, a minor repair such as slipped or broken tiles costs £150-£350, and flashing or chimney work £250-£600. See our roofing costs guide for the full breakdown. Insurance is best kept for major damage, such as storm damage across a large section of roof.
Need a roof inspection or report for a claim?
If the damage was sudden and unavoidable, you have a strong case. If it built up over time, insurers will almost certainly turn it down. The best protection is to maintain your roof properly and deal with problems early.
If you are unsure whether your roof damage would be covered, Alliance Roofing can help. We carry out honest roof inspections, emergency and planned roof repairs, and written assessments to support insurance claims. Based in Woking, we cover Surrey, east Berkshire and south-west London, including Chobham, Guildford and Richmond.